Know what you can spend
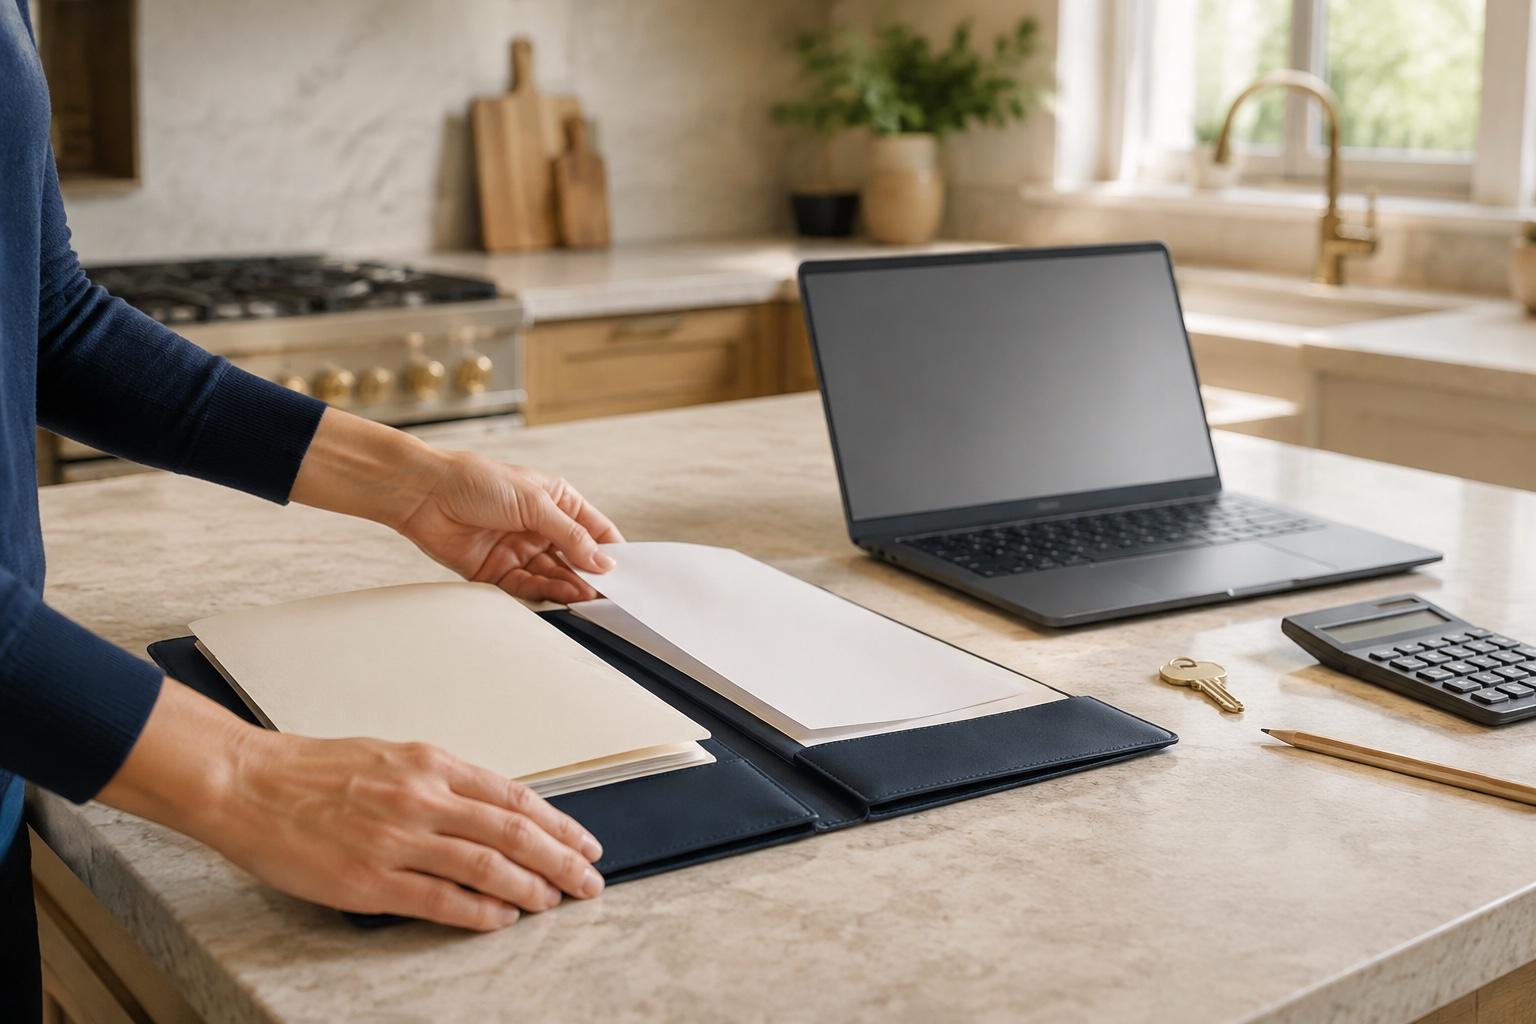
Gather your budget, lender questions, and notes about the home in one place. Then you can see what you know, what you need to check, and whether you are ready to make an offer.
Before a home catches your eye, decide what you can comfortably spend. Write down your price range, a monthly housing payment that feels manageable, and how much cash you want to keep after buying.
If you have a lender preapproval letter, note its date and any assumptions it lists. The Consumer Financial Protection Bureau (CFPB) says preapproval is tentative and based on assumptions; it does not guarantee a loan. Ask your lender what could change and when the letter expires, then use the letter to plan while keeping your own limits in view.
Keep lender answers handy and private records secure
Ask your lender which assumptions they used about your income, assets, debts, whether you will live in the home, and the type of property. Ask what documents you may need later and whom to call if something changes. Note when you last checked each answer.
The CFPB says preapproval does not commit you to that lender, so you can compare formal loan offers later. Keep Social Security numbers, account passwords, and full financial statements out of notes you may share about a home. Store those records in a protected system meant for sensitive information.
Make one page of notes for each home
Write down the address, asking price, your possible offer range, and the date you need an answer. Then list the questions that could change your decision:
- What would you need to learn from an inspection?
- Do you have questions about financing, the closing date, or what stays with the home?
- If the home needs work, can you still keep the cash reserve you planned?
Mark estimates and unknowns clearly. Ask your real estate professional or attorney how those questions should be addressed in the purchase contract. A general article cannot write those terms for your situation.
Check what has changed
Before you discuss an offer, take another look at the dates and facts. Is your preapproval still current? Has your budget changed, or have you taken on a new payment? Have you learned about a property cost you had not counted? Is the property information still current?
Write down when you checked. If an answer is old or uncertain, ask the person responsible for it to confirm it. Being ready means knowing what you can decide now and what still needs an answer. It does not mean giving up safeguards to move faster.